
YOUR QUESTIONS, ANSWERED
Big questions.Simple answers.
Honest answers from Abdallah H. Fragomeno, a Miami mortgage advisor with over 20 years of experience.
About Abdallah
How long have you been in the mortgage business?
Over 20 years. In that time I’ve helped first‑time buyers, families moving up, investors and homeowners refinancing, across nearly every loan scenario you can think of.
Which states are you licensed in?
Florida. I’m licensed throughout the state, NMLS 366447, with Premier Financial Group of Florida, LLC, NMLS 1318440.
Do you work in Spanish?
Yes. We work with clients in English and Spanish every day. For other languages, we can use translation tools to make sure you understand every step.
How is working with you different from a big bank or an online lender?
Two big differences. First, we’re local, so you can actually meet me in person, which matters when you’re making the biggest purchase of your life. Second, a bank can only offer its own programs. As a mortgage broker, we work with a variety of lenders, so we have loan programs for almost every scenario, and we compare terms and rates across them to find the best fit for you.
How quickly do you respond? Do you work evenings and weekends?
We usually reply within hours, and yes, answering on evenings and weekends is part of the job. Homes don’t wait for Monday.
Do you meet in person, or by phone and video?
All three. I prefer meeting in person, because I like to put a face to the voice, and this is most likely your largest purchase. If that doesn’t work for you, we can easily schedule a phone or video call.
What areas do you serve?
Mostly Miami‑Dade and Broward. Because I’m licensed throughout Florida, helping clients in Tampa, Orlando, Naples or Jacksonville is completely normal too.
Getting started
What’s the first step to get pre‑approved, and how long does it take?
The first step is a quick intro conversation so I can understand your situation and goals. From there, pre‑approvals usually come back within 24 hours once we have your documents.
Does getting pre‑approved hurt my credit?
Not with PREMIER. We pre-approve you with one soft credit check, which doesn't affect your credit score and isn't visible to other lenders. Every mortgage, including Non-QM loans, does require a full (hard) credit check before the loan is submitted to a lender. We run it only after you have a signed purchase contract and are ready to move forward, and we tell you before we do. That way your credit gets one full check, when it counts, not every time you look at homes.
What’s the difference between pre‑qualified and pre‑approved?
A pre‑qualification is a quick estimate of what you might borrow, based on information you tell us without verifying it. A pre‑approval is a formal review of your verified finances, and it shows sellers you’re a serious, qualified buyer.
How long does it take from application to closing?
Usually about 21 days. Some things outside the loan itself can affect timing, like the property’s title, repairs or the appraisal, and we keep you updated on all of it.
Credit, income & down payment
What’s the minimum credit score you can work with?
Every program has its own guidelines. For conventional loans, Fannie Mae no longer sets a fixed minimum score for loans approved through its automated underwriting (since November 2025); manually underwritten loans still have a minimum, and many lenders set their own, often around 620. FHA is generally around 580. VA has no official minimum, and some lenders go as low as 560. Your full picture matters too, so talk to me even if you’re close.
Which credit score do mortgage lenders use, FICO or VantageScore?
It depends on the loan program. As of October 2026, Fannie Mae and Freddie Mac accept either Classic FICO or VantageScore 4.0 for conventional loans, and VA loans accept both. FHA loans and manually underwritten conventional loans still use FICO. PREMIER can review both, and when the loan program and lender allow it, we use the model that works better for you. Everyone on the same loan is scored with the same model. The score in your credit app may not be the one a mortgage lender uses, so ask us before you decide where you stand.
How much down payment do I really need?
Less than most people think, and you don’t always need a big down payment. VA loans offer no down payment for eligible veterans and service members, subject to VA and lender guidelines. FHA is known for a low down payment, and conventional loans have low‑down‑payment options too. Down‑payment assistance programs can lower what you bring to closing even further, based on eligibility and available funds. I’ll show you exactly what applies to you.
Can I use gift money from family for the down payment?
Yes. Gift funds can be used toward the down payment on a primary home, a second home and, with some loan programs, even an investment property.
Do you help self‑employed borrowers?
Yes, and we have flexible self‑employed programs. The most common options qualify you with bank statements or your company’s profit‑and‑loss statement, and tax returns can be used too. Some programs don’t require income documents at all, but they need a larger down payment. It all depends on the program and your eligibility.
Can you help if I just started a new job or changed jobs recently?
Yes. A new or recent job can work. In some cases your education can even count as job history. For example, if you just graduated with an accounting degree and were hired as an accountant, your schooling can count in place of prior work experience.
Can you help buyers with an ITIN, or who aren’t U.S. citizens?
Yes. We offer ITIN loans and programs for non‑U.S. citizens, including permanent residents and work‑visa holders, some with minimal documentation and a streamlined process.
Can I buy a home after a bankruptcy, foreclosure or short sale?
Yes. The waiting period depends on the loan program and your down payment. FHA and conventional loans generally require about a two‑year wait, while some alternative programs have much shorter waiting periods. Contact me and I’ll tell you what applies to your situation.
Loan types
Which loan types do you offer?
FHA, VA, conventional, jumbo, DSCR and investor loans, bank‑statement and profit‑and‑loss loans, ITIN loans, and more. We also offer physician (doctor) loans for eligible medical professionals, and HELOCs for primary homes, second homes and investment properties. Physician loan programs can go well above the conforming limit, and some offer low or no down payment. Some lenders offer loan amounts up to $2.5 million, depending on credit score, debt‑to‑income ratio and other guidelines (as of October 2026).
Are there down‑payment assistance programs in Florida?
Yes. We work with down‑payment assistance programs, most commonly Florida’s Hometown Heroes program. Every program is based on eligibility and available funds, so ask me what you may qualify for.
Can you finance condos in Miami, including non‑warrantable buildings?
Yes, including non‑warrantable condos. Condo guidelines change often, especially in Florida, so reach out and I’ll check the specific building for you.
Do you do loans for investment properties or second homes?
Yes, both, including DSCR loans that qualify based on the property’s rental income.
Refinancing
When does refinancing make sense?
There’s no single rule of thumb. It depends on your goals, like lowering your payment, consolidating debt, freeing up cash for investments or improving monthly cash flow. I’ll run the numbers with you and tell you honestly if it makes sense.
Do you offer cash‑out refinances?
Yes, several types, whether you want to consolidate debt, renovate or invest, and I’ll give you a realistic timeline up front. We also offer HELOCs, which let you borrow against your equity and keep your current first mortgage. Some lenders use an automated home value instead of a full appraisal, which can shorten the timeline. On your primary home, funds are released after a 3‑business‑day right to cancel.
Do you do VA and FHA streamline refinances?
Yes. Both generally require about six months of payments on your current loan, and we can start the process as early as month five.
Costs & after closing
What closing costs should I expect in Florida?
Closing costs vary a lot depending on the loan program, occupancy, credit score, property taxes, title fees, HOA, homeowners insurance and flood insurance. That’s not a way to dodge the question. It’s the honest answer, and it’s why I’ll give you a real estimate for your situation.
Can the seller pay some of my closing costs?
Yes. Seller concessions typically range from 3% to 9% of the price, depending on the loan program, your down payment and how you’ll use the property.
Will you stay in touch after closing?
Of course. I love staying in touch with past clients, keeping an eye out for ways to save you money and helping with whatever comes next.
What’s your #1 advice for first‑time buyers in Miami?
Don’t rule yourself out too early. Many buyers think they need a big down payment, a 740 credit score or perfect tax returns, or they don’t know that gift funds and seller credits can help. Talk to a loan advisor who offers a wide range of programs, not just the bank where you do your everyday banking.
YOUR MORTGAGE ADVISOR
Nice to meet you.I'm Abdallah.
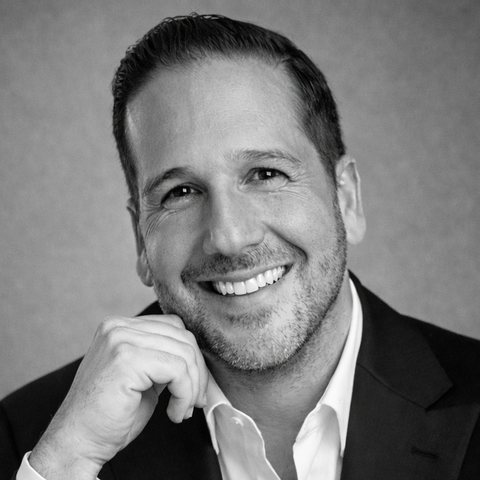
Your trusted Miami mortgage advisor. I'm here to make your home financing simple and stress-free.
Abdallah H. Fragomeno · Mortgage Advisor · NMLS ID 366447
Prefer the office? Team line: 888.718.4440
Texting is optional. Message and data rates may apply. Reply STOP to opt out or HELP for help. Privacy policy.

Ready, set,pre-approved.
Apply online, then send the documents on my checklist. I'll take it from there.